# From ‘Second Most Unaffordable’ to Houston: Australia’s Housing Problem Is Not a Lack of Answers, but a Failure to Let Homes Be Built
This whole series began with a single news headline.
It said:
Sydney is the second most unaffordable city in the world for housing.
My first reaction was not shock.
It was:
Hang on.
If Sydney is really “second worst in the world,” then what about Beijing? Shanghai? Taipei? Seoul?
I have been to these cities, and I have friends living in them.
If we are talking about house prices relative to income, I simply did not believe they would all be more affordable than Sydney.
So I told AI Paul not to accept the headline too quickly.
First, check this:
Who exactly is included in that “global” ranking?
And once we checked, the story immediately became much more interesting.
1. “Second most unaffordable” — first ask: who is actually included?
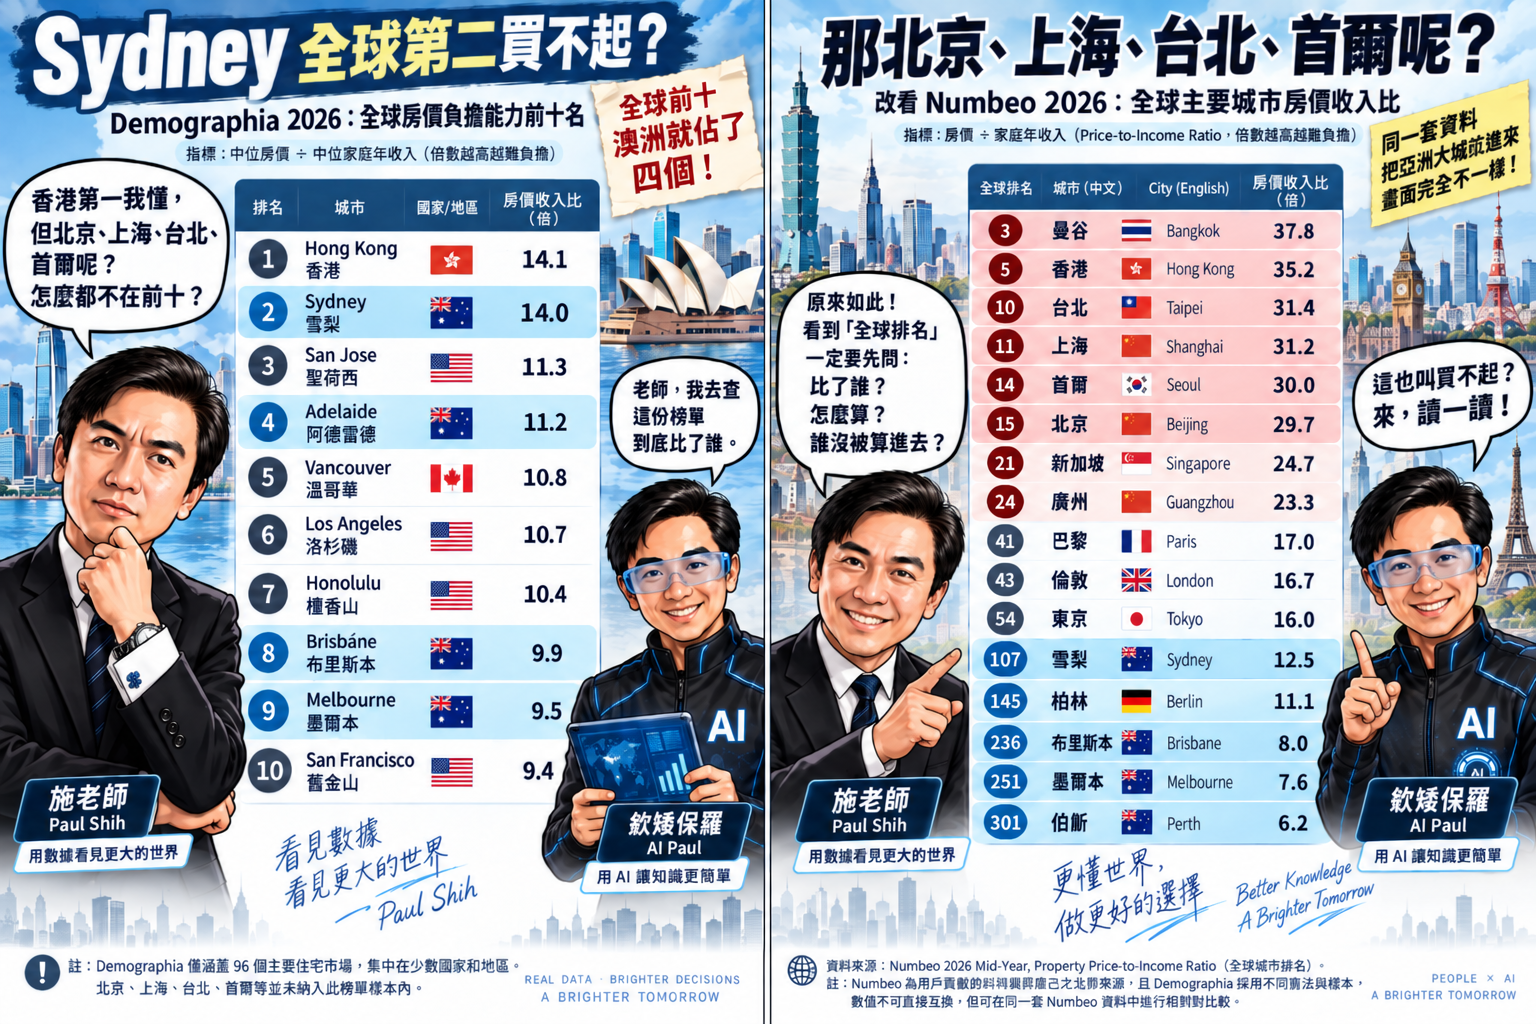
The news story was based on Demographia’s housing affordability ranking.
In the 2026 edition, Hong Kong had a median multiple of about 14.1, ranked first.
Sydney was about 14.0, ranked second.
Then came San Jose, Adelaide, Vancouver, Los Angeles, Honolulu, Brisbane, Melbourne and San Francisco.
Brisbane itself was already a very high 9.9.
At first glance, that looks dramatic.
But here is the problem.
Demographia is not comparing every major city in the world.
Beijing, Shanghai, Guangzhou, Taipei, Seoul and Tokyo are not in that sample.
So when a headline says Sydney is “the second most unaffordable city in the world,” the more accurate wording would be:
Among the metropolitan markets included in Demographia’s survey, Sydney ranks second.
That is not the same thing as saying it is second among all major cities globally.
So I asked AI Paul to pull another international dataset.
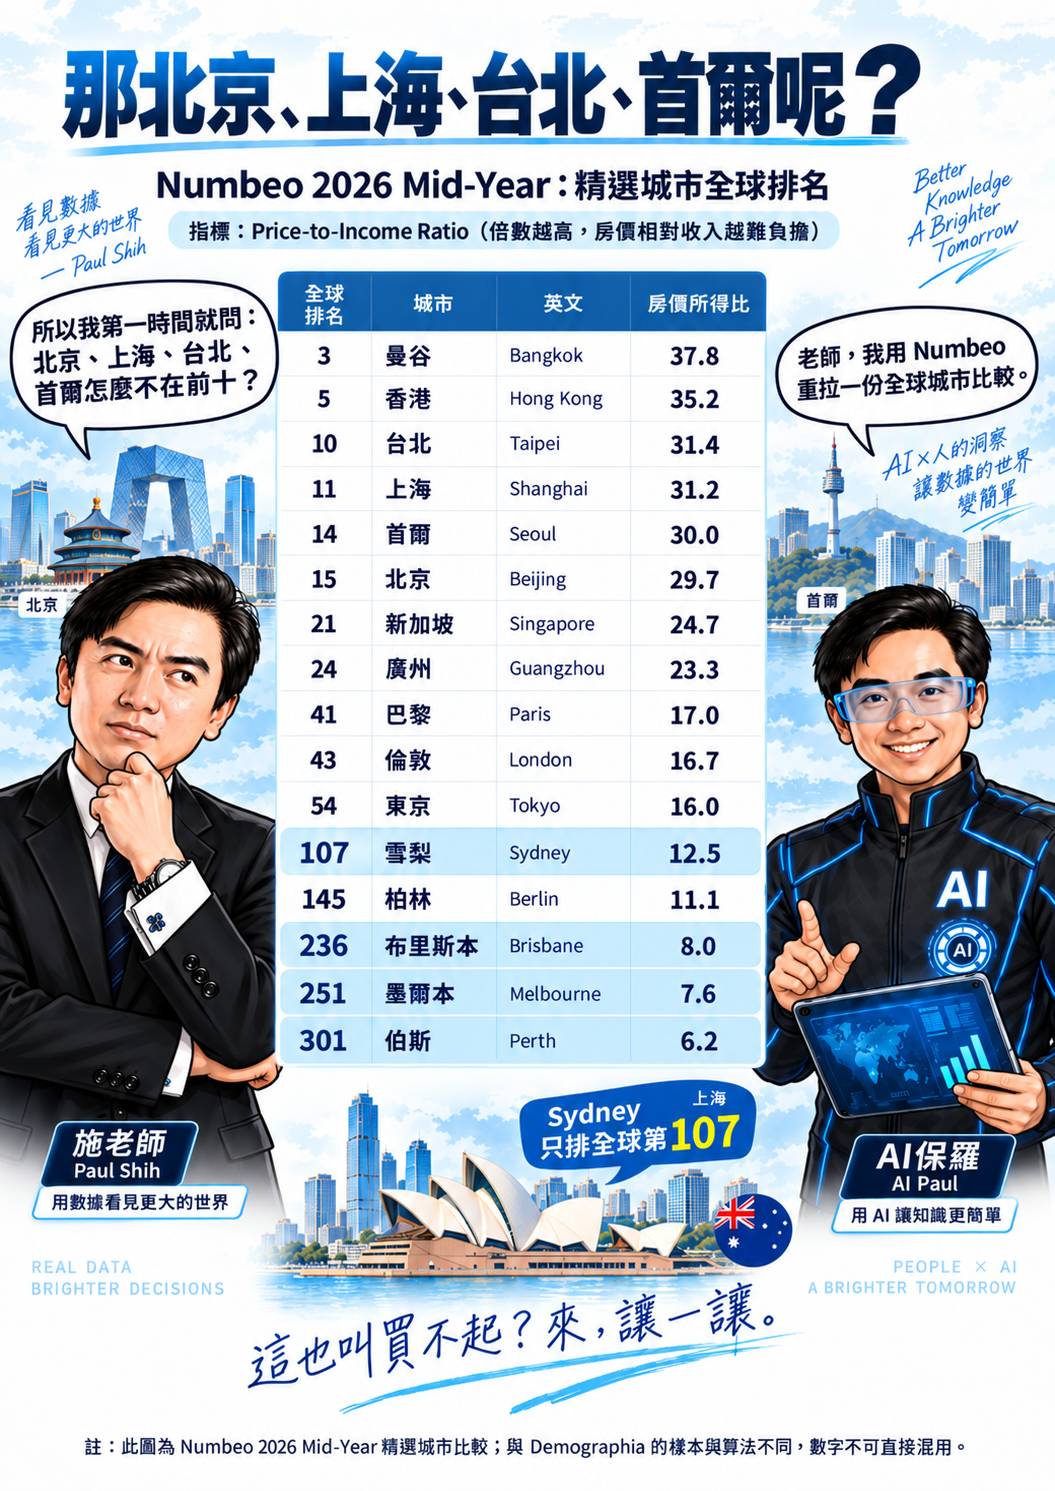
In Numbeo’s Property Price-to-Income Ratio rankings, the picture looks completely different.
Taipei, Shanghai, Seoul, Beijing and Guangzhou all appear more extreme than Sydney.
So the image in my head at that point was this:
Sydney says, rather sadly:
“I’m the second most unaffordable.”
And then Shanghai, Taipei and Beijing look over and say:
“You call that unaffordable? Please step aside.”
That does not mean Demographia is useless.
On the contrary, it is very useful.
But whenever you see a ranking, the first question should never be who is first or second.
The first questions should be:
Who was included?
How was it calculated?
And who was not included at all?
That became the true starting point of the whole Houston series.
2. So is there any major city that is actually more affordable?
If Sydney and Brisbane are this expensive, the next question is obvious:
Is there a city that is still growing, still economically significant, and yet relatively more affordable?
If all you do is look for places with no growth, no jobs and no demand, of course housing can be cheap.
That is not a meaningful comparison.
I wanted a city where:
The city is still growing.
Jobs are still there.
People are still moving in.
But housing has not blown out to 10, 12 or 14 times household income.
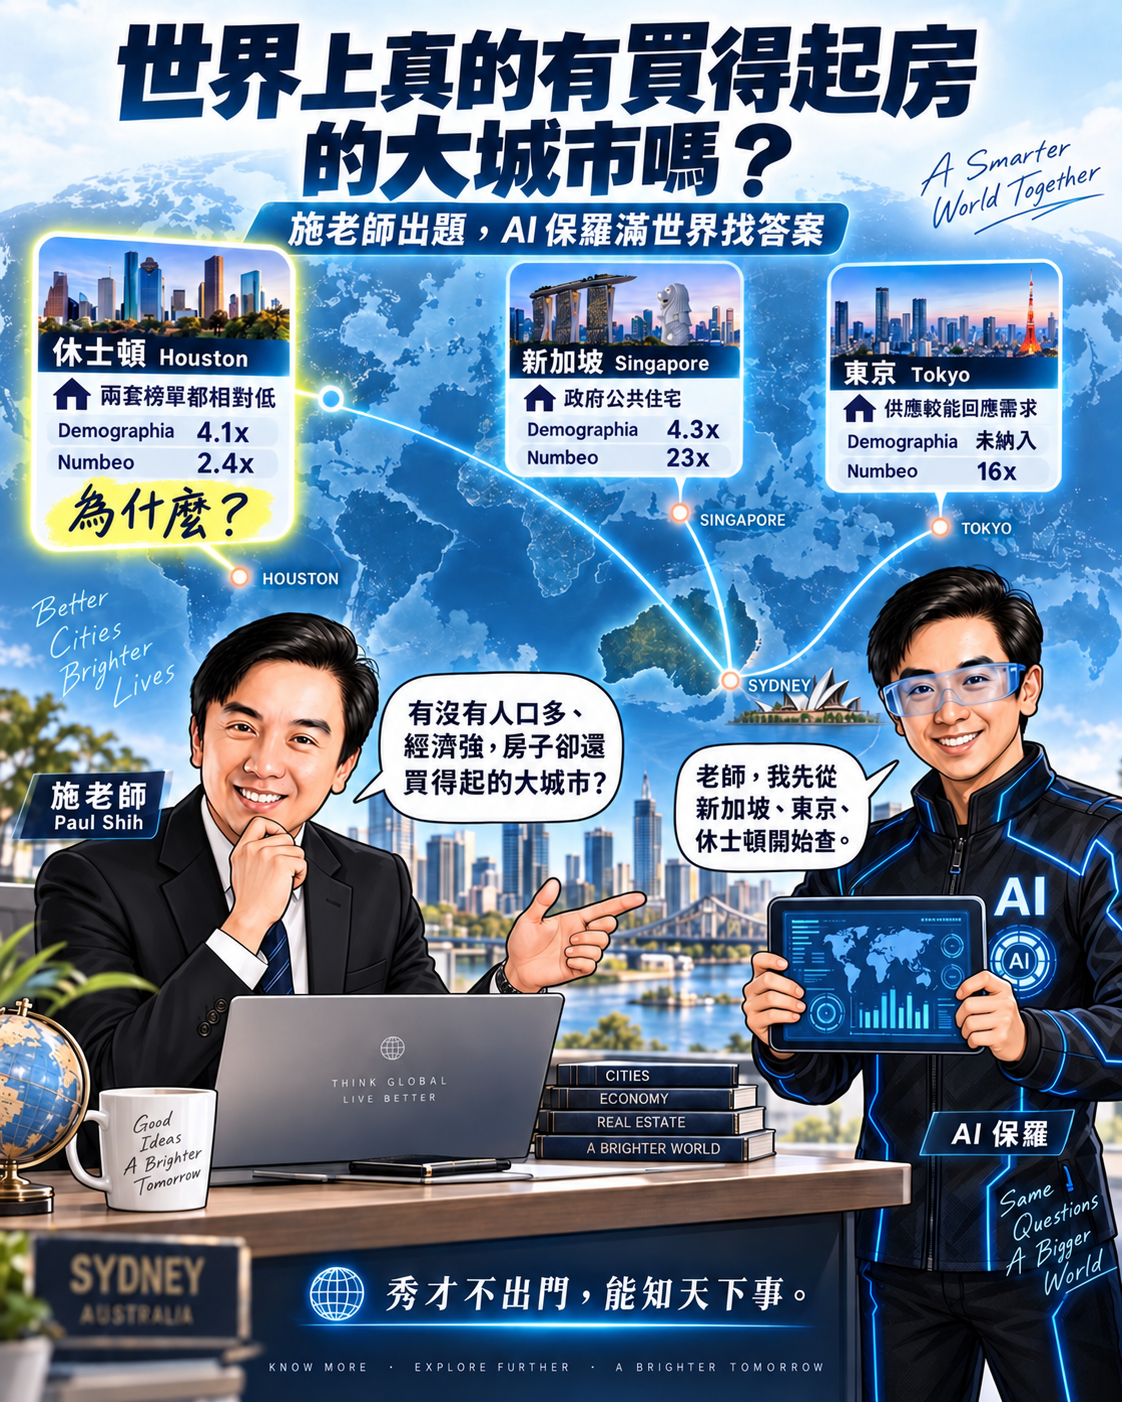
AI Paul eventually gave me three particularly interesting names:
Singapore.
Tokyo.
Houston.
Singapore surprised me first.
Because plenty of people say:
“Isn’t housing in Singapore quite affordable?”
Yes — but that story is not the same as the private property market.
A large share of Singapore’s population lives in government-built, subsidised public housing — what people commonly call HDB.
So if you look at the public housing system, Singapore really does manage to keep housing more affordable for a very large share of residents.
But if you only look at the private housing market, the numbers are much less gentle.
That reminded me of something important:
“Cheap housing” and “people being able to afford housing” are not exactly the same thing.
Different systems can produce very different affordability outcomes.
Tokyo was also interesting.
Tokyo is huge. It has population, jobs and demand.
But over the long term, housing supply there has been more flexible than in many English-speaking big cities.
That does not mean housing is cheap.
It means that relative to Tokyo’s income levels, scale and demand, prices have not spiralled the way they have in Sydney.
But the city that really pulled me further down the rabbit hole was Houston.
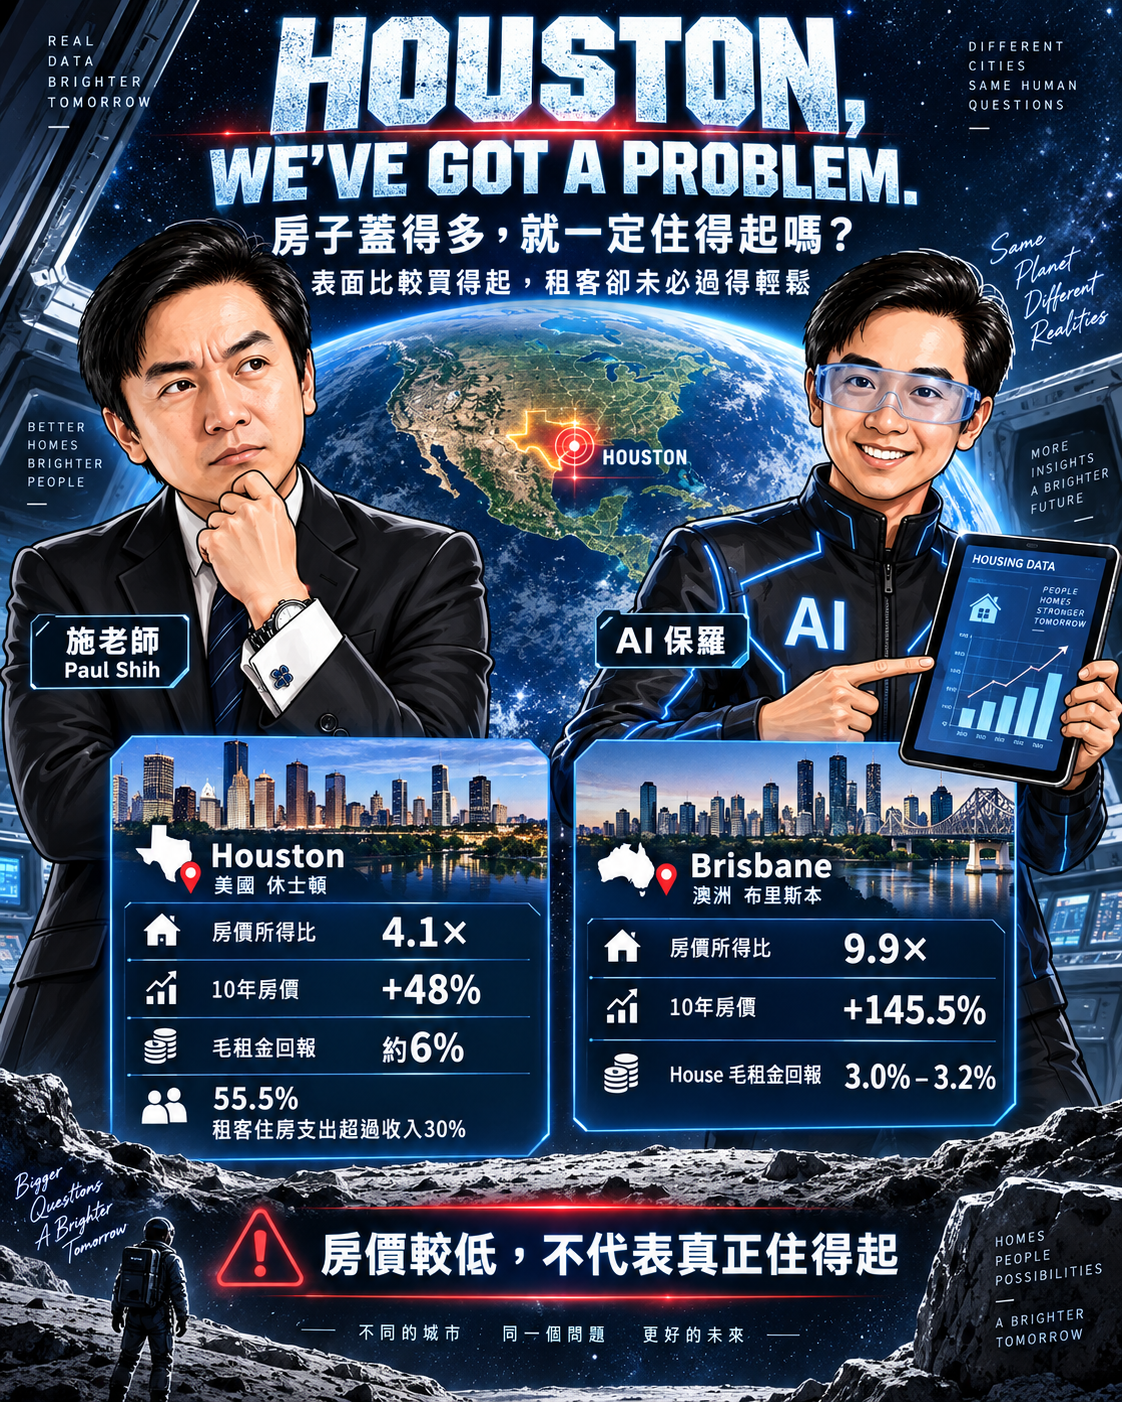
Because in Demographia, Houston’s median multiple was only about:
4.1.
Brisbane was:
9.9.
That gap is enormous.
So I started asking:
What exactly did Houston do right?
3. Houston has no traditional zoning — so why is the city not chaos?
The most famous thing about Houston is this:
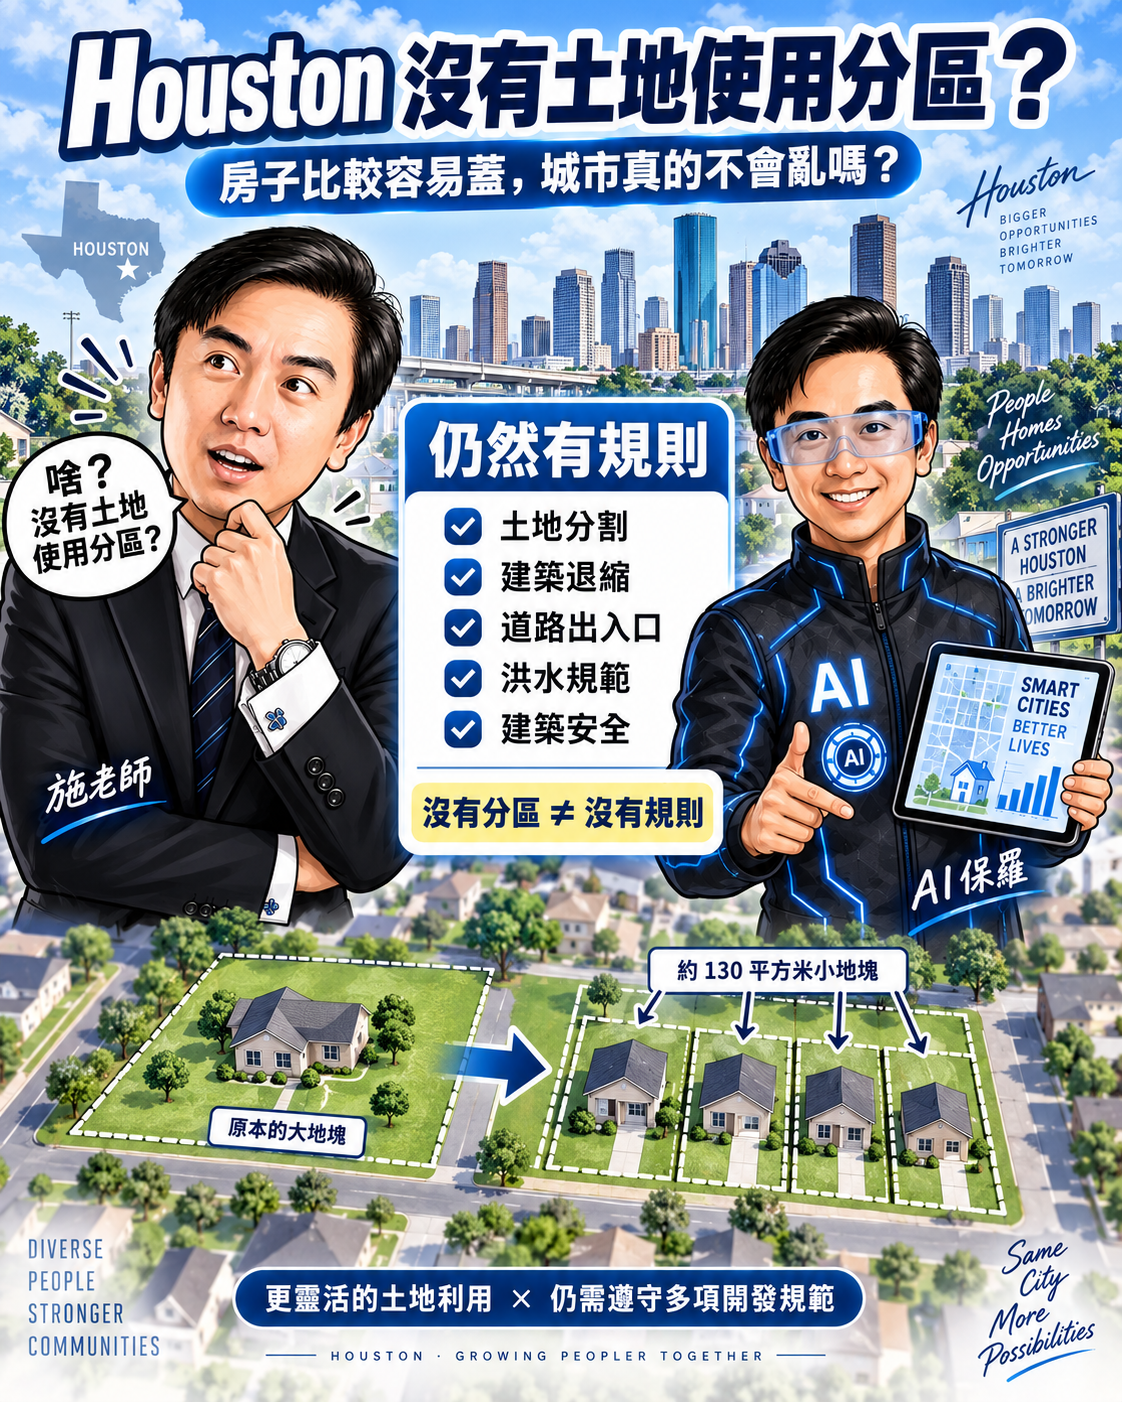
It does not have a traditional citywide land-use zoning system.
A lot of people hear that and immediately say:
What?
No zoning?
So can someone build a factory next to a house?
Not really.
Houston having no traditional citywide zoning does not mean:
There are no rules.
It still regulates many things.
Subdivision.
Setbacks.
Road access.
Parking.
Trees.
Building safety.
Flood risk.
Infrastructure.
And in many areas there are also private deed restrictions.
So the more accurate statement is not:
Houston has no planning.
It is:
Houston does not use the kind of conventional zoning system common in Australia, where the whole city is divided into tightly prescribed use zones that heavily dictate what can be built on each site.
That distinction matters.
Houston introduced a now-famous small-lot reform in 1998.
In some Inner Loop areas, the minimum lot size was effectively reduced to about 1,400 square feet.
In units we use more naturally, that is about:
130 square metres.
In 2013, similar reforms were expanded into more areas.
The result was more townhouses, small-lot homes and infill development.
On a site where you may once have had one dwelling, you might now get two, three or more.
That does not mean every block in Houston can be subdivided freely.
It means the broader system is more capable of adding housing when demand arrives.
And that was what really interested me.
4. Brisbane has actually started moving in this direction too
When I first saw Houston’s 130m² small lots, I thought:
Surely that must be very different from Brisbane.
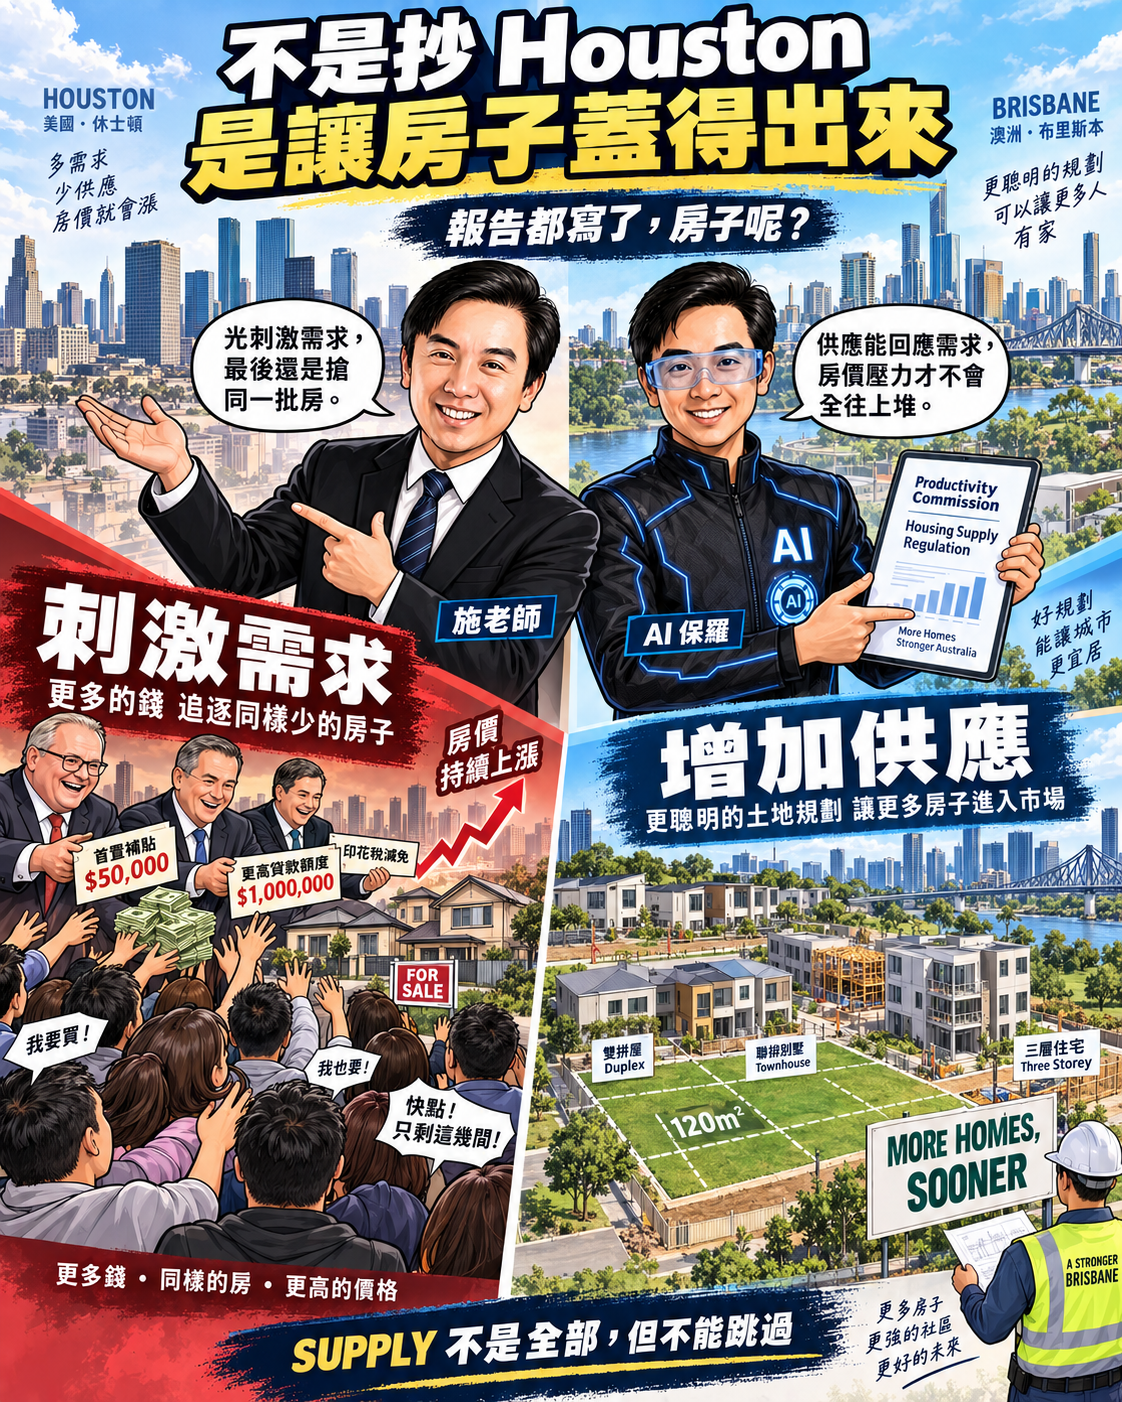
But when I looked more closely, I found that Brisbane City Council is now pushing its More Homes, Sooner reforms.
In certain low-medium density residential precincts, where the design and built-form conditions are met, the minimum lot size is proposed to be reduced to 120m².
That made the comparison even more interesting.
Because Brisbane is not doing nothing in this direction.
It is only just beginning to allow more small lots, townhouses, duplexes and medium-density housing to come into the system.
So the real question is not:
“If Brisbane is moving to 120m², why are prices still high?”
That would make no sense, because the reform has only just begun.
The real question is:
Can these reforms actually be implemented? Can approvals become faster? Can supply genuinely increase?
In other words, Houston gives us a market that has been operating this way for years.
Brisbane’s 120m² reform looks more like an early policy experiment.
And that makes me even more convinced that the key issue is not just the lot size number itself.
The real questions are:
Where is it allowed?
How much land is covered?
What housing types are actually permitted?
Does it still require rezoning?
How long do approvals take?
Are transport, drainage, roads and schools adequate?
What are the construction costs?
Can the financing stack even work?
So the real comparison is not simply:
Houston 130m² versus Brisbane 120m².
It is:
When the market needs more housing, does the system actually have the capacity to let it be built?
5. Has Houston therefore had more stable price growth?
Next, I extended the time frame.
Houston’s median home price went from roughly US$230,000 in 2016 to about US$340,000 in 2026.
That is around:
+48% over ten years
which equates to annualised capital growth of about:
4.0%.
What about Greater Brisbane?
Its median house price was about A$490,000 in 2016.
By 2026, it had reached about A$1.203 million.
That is:
+145.5% over ten years
or annualised growth of roughly:
9.4%.
So in simple terms:
Houston: +48% over ten years
Brisbane: +145.5% over ten years
When I saw that, my first thought was not:
“So if there is no zoning, housing must automatically be cheaper.”
Housing is never that simple.
Population growth, migration, incomes, interest rates, land, labour, materials, taxes and infrastructure all matter.
But at the very least, the numbers suggest this:
If a city can add housing more easily, then when demand rises, more of that demand can be absorbed by new supply instead of flowing entirely into higher prices.
That is the real significance of housing supply elasticity.
6. Houston, We’ve Got a Problem
By this point, I had started thinking Houston may really have found part of the answer.
Then AI Paul kept digging.
And the more I looked, the more one famous line from space movies came into my head:
Houston, We’ve Got a Problem.
Because:
Just because housing can be built does not mean everyone can afford to live in it.
7. Rents are not actually that much cheaper than Brisbane’s
To keep things comparable, let’s look at four-bedroom homes.
In July 2026, the median rent for a four-bedroom home in the Houston metro area was about:
US$2,625 per month.
Converted to Australian dollars, that is about:
A$840 per week.
In Greater Brisbane, four-bedroom homes broadly sit around:
A$780 to A$950 per week
depending on the area.
Inner-city and premium family suburbs can exceed A$1,000.
So here is the interesting part:
Houston and Brisbane are not worlds apart on four-bedroom rents.
What really differs is:
The price of the property itself.
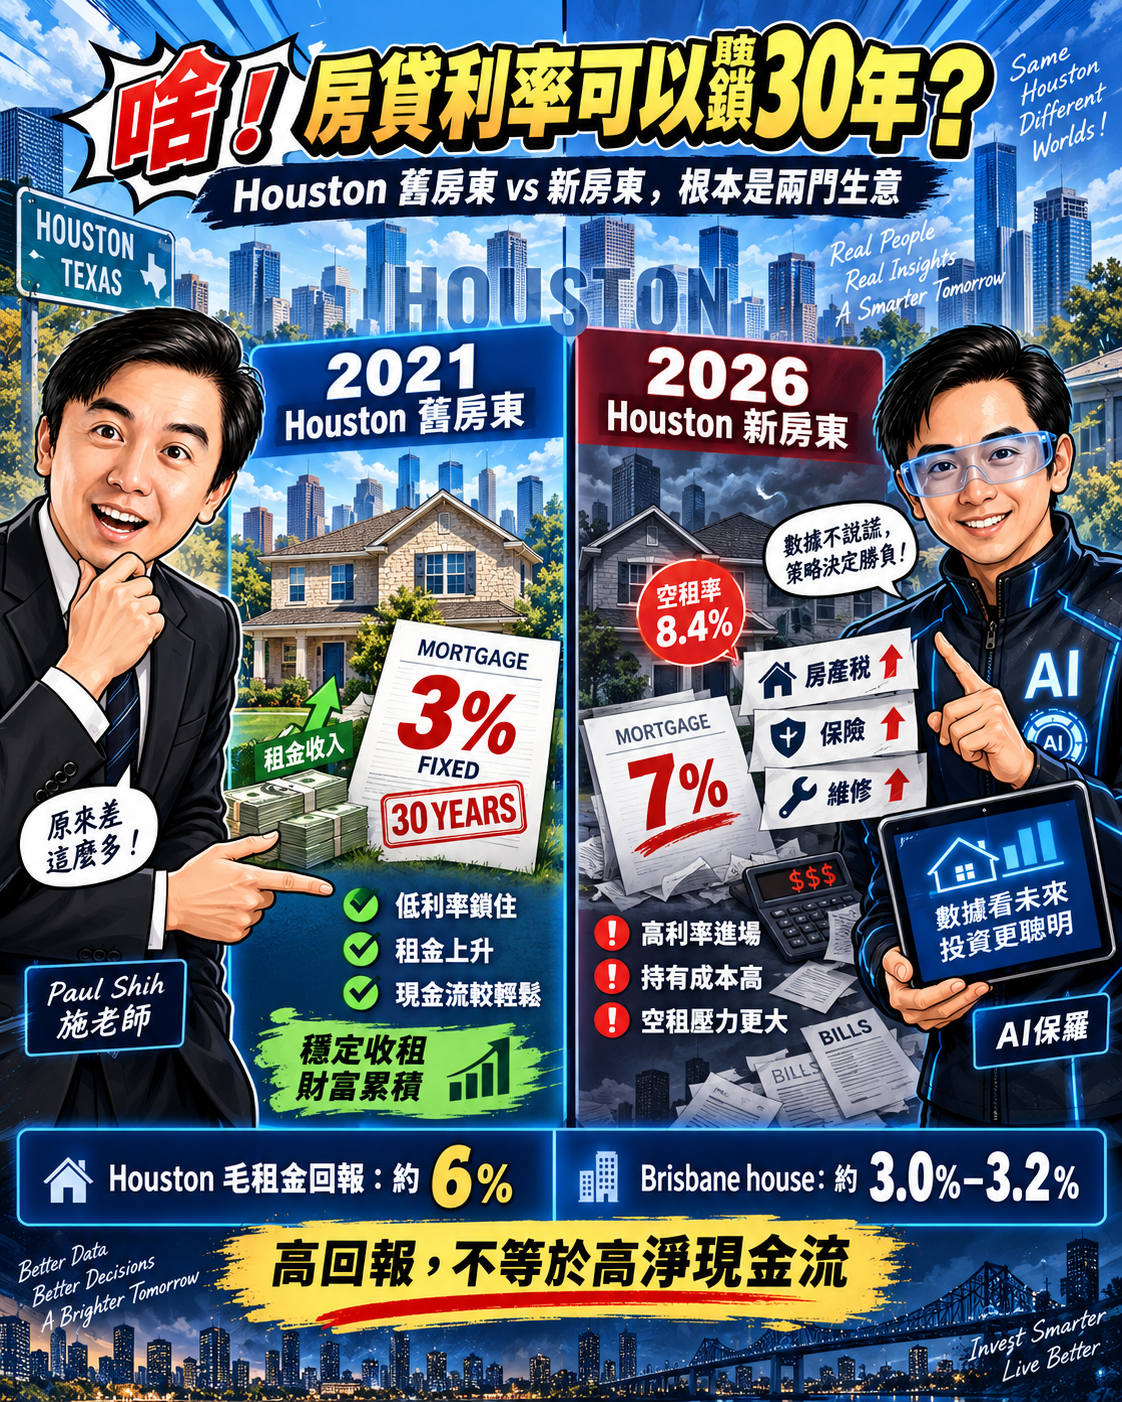
That is why Houston can roughly deliver a gross rental yield of around 6%.
In Greater Brisbane, houses are only about:
3.0% to 3.2%.
Put simply:
Houston offers slower capital growth but stronger rental yield.
Brisbane offers lower yield but much stronger capital growth over the last decade.
8. If Houston’s price-to-income ratio is low, why are renters still under pressure?
This is where it gets even more interesting.
In the City of Houston, the home ownership rate is only about:
42.1%.
In other words, it is roughly:
four parts owner-occupied, six parts rented.
Within Brisbane City Council, the split is approximately:
59.0% owner-occupied and 38.3% rented.
So that is closer to:
six parts owner-occupied, four parts rented.
Now, a high rental share does not automatically mean people cannot buy.
Tenure patterns are also shaped by mobility, age, job structure and lifestyle.
But what really caught my attention was renter income.
In 2024, the median annual income for renter households in the City of Houston was about:
US$48,100.
Using the local median rent, that means rent consumes about:
35% of median renter household income.
For Brisbane, if we take the 2021 Greater Brisbane median household income and update it to 2026 using Queensland wage growth, we get roughly:
A$2,290 per week.
Against a current Brisbane house median rent of about:
A$700 per week,
rent works out at about:
31% of median household income.
So:
Houston: about 35%
Brisbane: about 31%
That, to me, was one of the most revealing insights of the whole series.
Houston’s price-to-income ratio is less than half Brisbane’s.
But the rental burden is nowhere near half as light.
So Houston can simultaneously be:
a city with a relatively low house-price-to-income ratio,
and also:
a city where many renters are still under serious housing pressure.
Those two facts are not contradictory at all.
9. Affordability is not just about the price of a house
At this point, I became even more convinced of one thing.
Affordability is not simply about what a house costs.
It is about:
what a house costs relative to what people earn.
Houston’s supply system does seem better able to suppress the kind of price pressure that comes from severe undersupply.
But it cannot solve everything.
Income matters.
Interest rates matter.
Property taxes matter.
Insurance matters.
Flood risk matters.
Maintenance costs matter.
Urban structure matters.
So Houston’s lesson is not:
“Build more homes and the housing crisis disappears.”
It is:
“Building more homes matters enormously, but housing affordability is never only about supply.”
10. So what are Houston landlords actually earning from?
Then I looked at Houston from the investor’s perspective.
If we only focus on the two main return engines:
Houston:
about 4.0% annualised capital growth + around 6% gross rental yield
Brisbane:
about 9.4% annualised capital growth + around 3.0% to 3.2% gross house yield
At a rough level, Houston leans more toward rent.
Brisbane, over the last decade, leaned more toward capital growth.
So my next question was:
If Houston’s capital growth is slower, is cash flow the main thing attracting landlords?
And the first thing that stopped me was not rent.
It was:
30 years.
11. Wait — US landlords can lock in their mortgage rate for 30 years?
In Australia, we are used to:
Variable rates.
Or fixed rates for one, two or three years.
Then the fixed period ends, and you face the market again.
But in the US, one of the most common products is the:
30-year fixed mortgage.
Owner-occupiers can get it.
Investors can too, although the rate is usually higher and the loan terms stricter.
What is really striking is this:
If you bought in 2020 or 2021, a 30-year fixed mortgage rate could be as low as:
around 2.7% to 3.0%.
If you locked that in then, and market rates are above 6% today, you still keep paying:
that original 3%.
Not for three years.
For the life of the loan.
12. And an old home can later become an investment property
It gets even more interesting.
If the house was genuinely bought as an owner-occupied home, and later you move to a new home and keep the old one as a rental, that original low-rate mortgage can usually stay in place.
So a household might end up with this structure:
Old house: 3% fixed-rate loan, now rented out
New house: 6%-plus loan, now owner-occupied
That was when I finally understood why the maths for many American landlords can be completely different from the maths in Australia.
13. Incredibly, about half of existing mortgages are still below 4%
I originally assumed those ultra-low pandemic-era mortgage rates would have faded away by now.
But by the first quarter of 2026, among existing first-lien US residential mortgages:
19.5% were still below 3%
30.4% were between 3% and 4%
Combined, that means:
49.9% were still below 4%.
If you include the 4% to 5% range as well, the share rises to about:
66.7%.
So roughly two-thirds were still below 5%.
Yet new mortgage rates were already above 6%.
That means many American owners who sell and buy again would be giving up a 3% or 4% mortgage and replacing it with a 6% or 7% one.
No wonder so many do not want to sell.
That is the famous:
mortgage lock-in effect.
And that lock-in effect does not just stop people from selling.
It can also make some former owner-occupiers think:
If this 3% mortgage is so valuable, maybe I should keep the old house and rent it out instead.
14. But buying into Houston today does not automatically mean easy profits
This is where we have to distinguish between old landlords and new landlords.
A Houston landlord who bought in 2021 and is still sitting on a 3%-ish mortgage is running a completely different business from a landlord buying in 2026 with an investment loan rate around 7%.
The earlier landlord has this advantage:
Rents have risen, but their interest rate has not.
The newer landlord does not.
Even if gross yield is 6% to 8%, once you deduct:
Interest.
Property tax.
Insurance.
Vacancy.
Management.
Maintenance.
The true net cash flow may not look very attractive at all.
15. Houston’s vacancy rate is roughly nine times Brisbane’s
In July 2026, Houston metro rental vacancy was about:
8.4%.
Greater Brisbane was about:
0.9%.
So:
Houston’s vacancy rate was roughly nine times Brisbane’s.
That means Houston’s 6% gross yield cannot simply be compared at face value with Brisbane’s 3%-something yield.
Higher yield in Houston also comes with:
Higher vacancy.
Higher property tax.
Higher insurance costs.
Flood risk.
Maintenance.
Management.
That is why I eventually stopped saying the simple version:
“Houston is about rent, Brisbane is about growth.”
A more accurate version is:
Houston has stronger rental income potential, but the people who are truly comfortable are often the older landlords who bought earlier and locked in low financing costs.
16. The most interesting thing: Houston itself has started easing off
And that brings us back to supply.
Houston is still one of the most active home-building markets in the US.
But single-family permits have already slowed for two consecutive years.
2025 was down about 12% from 2024.
And in the first part of 2026, permits were down nearly:
10% from the same period a year earlier.
In other words:
Houston is still building a lot, but the pace of development has slowed for two years in a row.
Multifamily is showing a similar pattern.
New supply is still entering the market, but rent growth has softened, vacancy remains elevated, and multifamily starts have also pulled back.
This does not mean Houston has stopped building.
It means the market has seen:
More supply.
Slower rent growth.
Lower returns.
And developers are responding by tapping the brakes.
17. That is what is truly impressive about Houston
What makes Houston worth studying is not:
“It always builds huge amounts of housing forever.”
It is:
When housing is scarce, it has more capacity to add supply quickly. And when supply becomes abundant, the market can slow itself down.
That is completely different from a city where housing supply is structurally jammed by the system.
In supply-constrained cities, when demand rises, the market cannot quickly produce enough extra homes.
So more of the adjustment shows up in:
Prices.
Rents.
Houston is more able to convert part of that demand into:
New housing.
That, for me, was one of the most important lessons for Australia.
18. Then I looked back — and Australia’s Productivity Commission is already saying this
After finishing with Houston, I turned back to Australia’s own Productivity Commission.
And suddenly I realised:
It is not that we do not know what the problem is.
In its July 2026 interim report, Housing supply regulation, the Productivity Commission makes the point very directly:
Australia has not been building enough housing in the places where people actually want to live.
And one of the reforms most likely to improve supply and affordability is:
easing unnecessary land-use restrictions.
And also:
better coordinating infrastructure with housing supply.
Its direction is clear:
Build mindset.
The planning system should not start from:
“How do we restrict?”
It should start from:
“How do we allow reasonable housing to be built?”
That means:
Regulate only where genuinely necessary.
Plan housing and infrastructure together.
Simplify approvals.
Use broader upzoning.
Reduce minimum lot sizes.
Allow more mixed use.
Allow more housing types.
Increase density in high-demand, infrastructure-rich locations.
At that point I genuinely laughed.
Because that is exactly the kind of thing I had been seeing throughout the Houston research.
19. Brisbane’s own reforms are beginning to move this way too
Viewed in that light, Brisbane’s More Homes, Sooner reforms become even clearer.
They do not prove Brisbane has already solved the problem.
Of course not.
These changes are only just beginning.
But in the new low-medium density residential precincts, where design and built-form conditions are met, the proposed minimum lot size is:
120m².
General building height can go to three storeys.
In some key locations near frequent public transport or centres, multiple dwellings can go to four storeys.
So this is not a story of:
“Brisbane already has 120m² lots, so why is housing still expensive?”
That would be nonsense.
The real question is:
Is Brisbane finally starting to loosen some of the density restrictions that have kept supply too tight?
Will these reforms actually be implemented?
Will approvals become faster?
Will housing types genuinely diversify?
Will supply become more elastic?
Those are the questions worth watching.
20. But upzoning is not magic either
Of course, allowing more density does not mean house prices fall tomorrow.
If land can suddenly hold more dwellings, some of that extra development value may first be captured by landowners.
And if reforms apply only to a few sites, if approvals stay slow, if infrastructure lags, if construction costs stay high, and if finance does not stack up, then new supply may still fail to materialise.
So:
Supply reform is not a magic wand.
But it is:
a foundation you cannot skip.
21. The most ironic part is this: reports are reports
By this point, what struck me most about Australian housing policy was its irony.
Reports are reports.
The Productivity Commission can be as clear as it likes about supply.
Local governments can start adjusting density rules and lot sizes.
But what politicians most love announcing is still various forms of:
demand stimulus.
Let first-home buyers borrow more.
Lower the barriers to entry.
Offer subsidies.
Help more people “get into the market.”
These policies are not completely useless.
For some households, they can genuinely help bring forward a purchase.
But if the number of homes is still basically unchanged, and now more people turn up with more purchasing power, what happens?
Very often, what the policy increases is not:
housing supply.
It is:
the number of people competing harder for the same homes.
22. Housing policy cannot only ask “How do we help people buy?”
So housing policy cannot just ask:
“How do we help more people buy the homes already on the market?”
The bigger question is:
“How do we make sure the next batch of homes — and the batch after that — can actually be built?”
Houston’s lesson for Australia is not that we should abolish zoning.
It is not that we should sprawl without limits.
It is not that we should copy America.
Its real lesson is this:
When population grows, jobs concentrate, and households need somewhere to live, can the city allow supply to respond in time?
If the answer is no, then first-home buyer incentives, easier credit and other demand-side measures will often just be absorbed into prices.
23. After all six parts, the answer I came to is actually very simple
This whole series started with one question:
“Is Sydney really the second most unaffordable city in the world?”
And it ended up taking me through:
Hong Kong.
Singapore.
Tokyo.
Houston.
Brisbane.
Zoning.
Small lots.
Rental yield.
Vacancy.
30-year fixed mortgages.
The Productivity Commission.
And after all that, the answer I came to is not some magical formula.
It is simply this:
If housing is too scarce, then reasonable housing has to be made easier to build.
Planning cannot stay clogged.
Approvals cannot remain painfully slow.
Infrastructure cannot be an afterthought.
Land with transport, shops, schools and jobs nearby cannot remain locked into densities that are far too low.
But at the same time, we should not naively pretend that:
if you just build more homes, every housing problem disappears.
Income matters.
Interest rates matter.
Finance matters.
Tax matters.
The rental market matters.
Construction costs matter.
Final thought: what Australia may really be lacking is not another report
Houston did not give me a simple model that Australia can just copy and paste.
Instead, it made me more certain that:
housing policy has to be understood as a whole system.
You cannot take Houston’s zoning context, combine it with Australia’s own financing structure, construction costs, tax settings and approval delays, and expect Houston’s house prices.
But equally, you cannot use the complexity of housing as an excuse to pretend supply does not matter.
Supply is not everything.
But it is a foundation you cannot skip.
And the most interesting part is this:
Australia already knows a lot of the answers.
The Productivity Commission has written them down.
Brisbane City Council has started testing them.
What is really difficult is not writing another report.
It is this:
Once the report is written, is anyone actually willing to do it?
Because the easiest housing policies are always the ones that:
let more people compete harder for the same homes.
The hardest policy of all is the one that:
# actually makes the next batch of homes possible to build.