When I see POA, I can't be bothered calling
Students, here’s something I often say in class.
When I used to look at properties, one of my pet hates was seeing “POA” in the price field.
Price on Application.
Beautiful photos. A glowing description. But no indication of what it costs.
I just want to know whether I can afford it. Do I really have to ring the agent and have a conversation first?
Eventually, whenever I saw POA, I simply couldn’t be bothered calling.
Another familiar version is “Contact Agent”. Much the same idea.
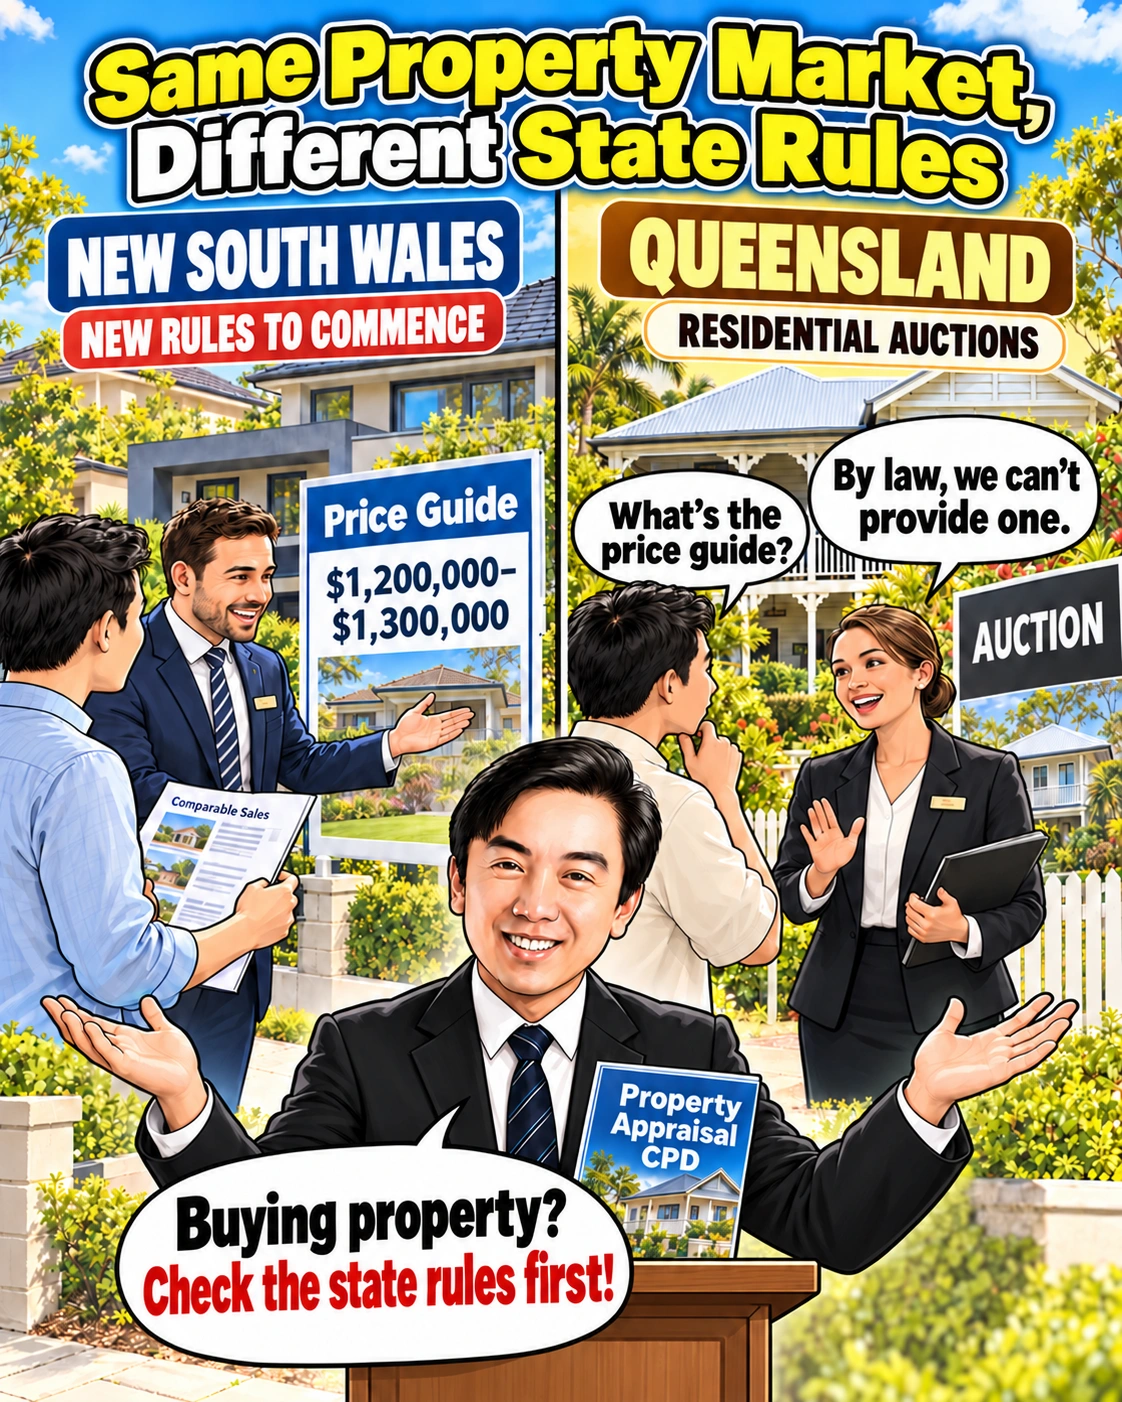
New South Wales is preparing to change this by requiring agents to include a selling price or price range in residential property advertisements.
A reminder before anyone gets excited: this is a NSW reform. Don’t read the news and immediately expect a Queensland agent to follow it!
State differences come up regularly in my CPD classes
When I teach property appraisal CPD, we often discuss how underquoting laws differ between states.
Selling a property in NSW and selling one in Queensland involve different rules. You cannot roll them into one.
For residential auctions in Queensland, agents are legally prohibited from giving buyers a price guide, disclosing the reserve price or indicating an amount they believe would secure a successful or acceptable bid.
So if you ask an agent about a Queensland auction property, “Come on, just give me a rough price!”, they cannot simply give you a figure. That is how the law works.
Ordinary non-auction sales can still be advertised with a price. Don’t turn “no price guides for Queensland residential auctions” into “no Queensland properties can have an advertised price”.
Cross a state border and the rules may change.
NSW wants agents to show how they arrived at the price
Alongside advertised prices, NSW’s reforms will require a Statement of Information containing comparable sales and other information to help buyers understand the pricing. Sale signs on or next to the property have an exception to the requirement to display a price.
Another change concerns rejected offers. If a seller rejects a written offer solely because the amount is too low, the agent will not be able to keep advertising a lower price.
For example, suppose someone makes a written offer of $1.2 million and the seller rejects it because it is too low. The agent cannot keep using $1.1 million to attract the next round of buyers.
If the offer was rejected because of finance, settlement or other conditions, that needs separate consideration. You cannot look at the dollar amount alone.
There is a sound reason for this reform.
Inspecting properties, reviewing contracts and arranging inspections all take time and money. Attracting people with a price you know will not buy the property wastes everyone’s time.
The changes are being introduced in stages. As at 25 October 2026, when this article was prepared, the commencement dates for mandatory advertised prices and Statements of Information remained subject to government announcement. They should not be described as already fully operational.
An official form still needs a critical reading
A buyer’s agent quoted in the news raised a useful concern.
Will buyers see a formal document and assume the price must be reliable?
Requiring an agent to provide information does not mean the government has guaranteed every appraisal.
Take two three-bedroom homes in the same suburb. One is in a quiet side street; the other fronts a main road. One has just been renovated; the other needs well over $100,000 of work.
Can you compare their sale prices directly just because both have three bedrooms?
Land size, the site’s slope, condition and the date of sale can all affect the price.
Which comparable properties are selected will influence the picture you see.
That does not mean you should distrust everything an agent provides. But you should understand why those properties are comparable to the one you want to buy.
And don’t treat the asking prices of properties still on the market as evidence of completed sales. What a seller wants and what the market will pay are different things.
A final sale price above the original price guide does not automatically establish unlawful underquoting either. The questions include whether the agent’s estimate was reasonable at the time and whether it was appropriately updated as new information became available.
Set your limit before you raise your hand
Greater transparency helps buyers check the information.
But remember that the selling agent has been engaged to sell the property for the seller. Buyers still need to research the market and decide their own spending limit.
In NSW, if there is a price guide, understand where it came from.
In Queensland, where residential auctions have no price guide, you have even more reason to do your homework.
What a property is worth, what the bank will lend you and what you are willing to pay are three different numbers.
Think them through separately.
Especially the last one. Decide it before you start bidding.
Don’t keep raising your budget every time you raise your hand.